Firms' costs, revenue and objectives
Costs of production
- Fixed cost (FC) - a cost that does not change with output in the short run, such as rent, insurance or a business licence.
- Variable cost (VC) - a cost that changes as output changes, such as raw materials, packaging or hourly production labour.
- Total cost (TC) - the complete cost of producing an output: fixed cost plus variable cost.
- Average fixed cost (AFC) - fixed cost per unit of output.
- Average variable cost (AVC) - variable cost per unit of output.
- Average total cost (ATC) - total cost per unit of output. It is also called average cost.
| Measure | Formula |
|---|---|
| Total cost | TC = FC + VC |
| Average fixed cost | AFC = FC / output |
| Average variable cost | AVC = VC / output |
| Average total cost | ATC = TC / output = AFC + AVC |
Worked cost example
A bakery has a fixed cost of $600. At an output of 300 loaves, its variable cost is $900.
- Find TC. $600 + $900 = $1500.
- Find AFC. $600 / 300 = $2 per loaf.
- Find AVC. $900 / 300 = $3 per loaf.
- Find ATC. $1500 / 300 = $5 per loaf, which also equals $2 + $3.
Calculation check: Keep totals and averages separate. A total is measured for all output; an average is measured per unit.
How output affects costs
Fixed cost stays unchanged as output changes, so the FC curve is horizontal. Variable cost and total cost rise as more output is produced, and the vertical gap between TC and VC equals fixed cost.
AFC continually falls because the same fixed cost is spread over more units. AVC and ATC may fall at first as resources are used more efficiently, then rise when overcrowding, bottlenecks or less efficient extra resources appear. ATC always lies above AVC because ATC includes average fixed cost.
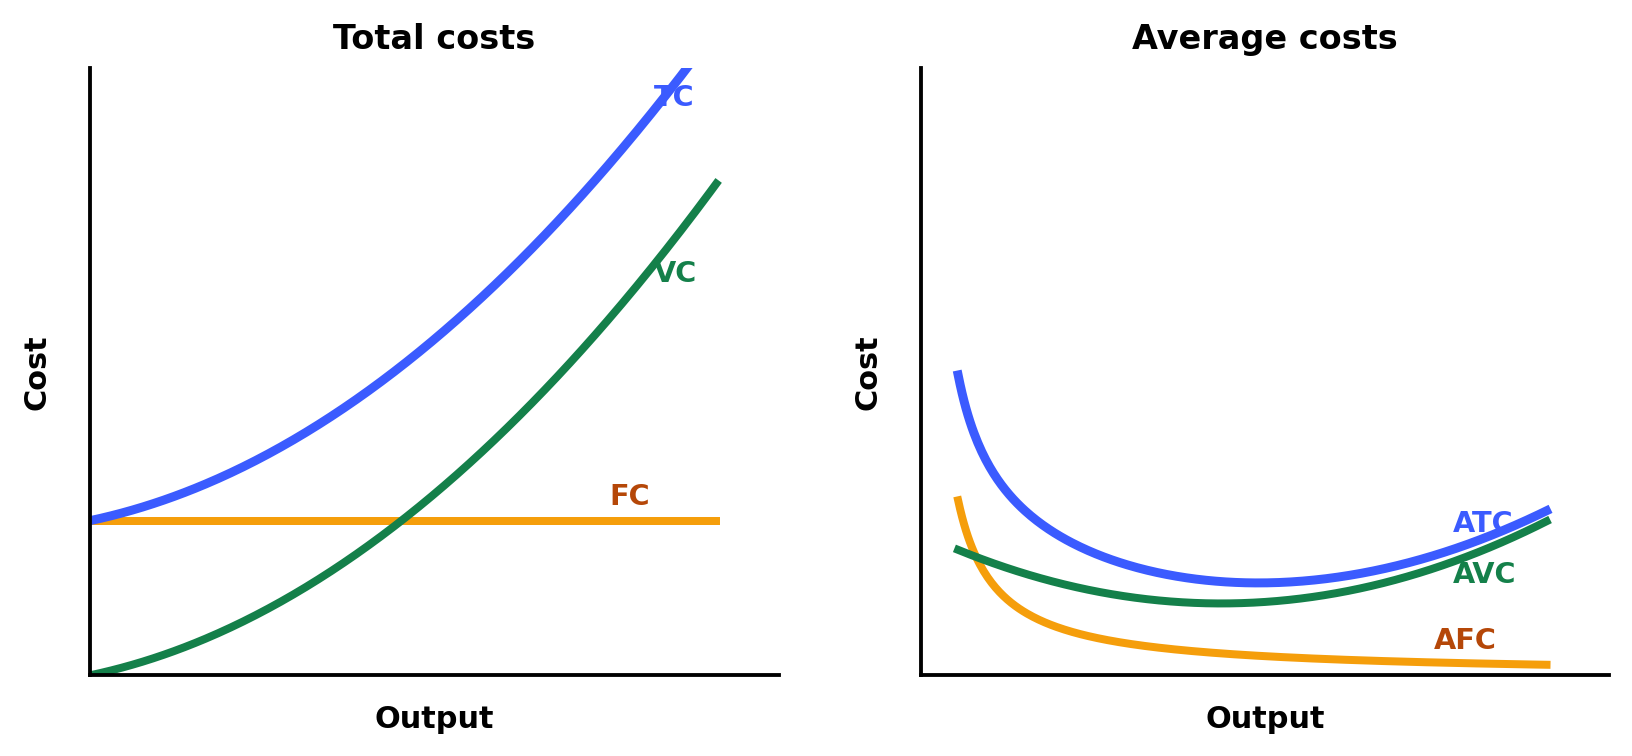
Figure 3.4: The required relationships between output and total or average costs.
Revenue
- Total revenue (TR) - the total money a firm receives from selling its output.
- Average revenue (AR) - revenue received per unit sold.
| Measure | Formula |
|---|---|
| Total revenue | TR = price x quantity sold |
| Average revenue | AR = TR / quantity sold |
If all units sell for the same price, average revenue equals that price. For example, selling 400 tickets at $5 produces TR of $2000 and AR of $5.
More sales increase total revenue when price is unchanged. If a firm cuts price to increase sales, TR may rise or fall: it rises when the percentage increase in quantity demanded is larger than the
percentage price fall, and falls when the sales response is smaller. This is the PED relationship studied in Unit 2.
Profit and objectives of firms
- Profit - the amount by which total revenue exceeds total cost.
Formula: Profit = total revenue - total cost
- Profit maximisation - trying to earn the greatest possible difference between total revenue and total cost.
- Growth - increasing the firm's sales, output, number of outlets, market share or productive capacity.
- Social welfare - the well-being of people and society, including workers, consumers, communities and the environment.
| Objective | Why a firm may pursue it | Possible conflict or limitation |
|---|---|---|
| Survival | A new or struggling firm needs enough revenue and cash to continue operating. | Low prices or cost-cutting may protect survival but delay growth and profit. |
| Profit maximisation | Profit rewards owners, finances investment and provides a buffer against risk. | Very high prices or low quality may damage reputation and future demand. |
| Growth | Managers or owners may want market power, economies of scale, status and higher future profit. | Rapid expansion can create debt, loss of control and diseconomies of scale. |
| Social welfare | Owners may value ethical aims; responsible behaviour can motivate workers and strengthen reputation. | Higher wages, safer inputs or environmental protection may raise short-run cost. |
Objectives can change. A new firm may prioritise survival, then growth, and later profit or social welfare. Public-sector organisations may give greater weight to access and welfare, while private owners may still accept lower short-run profit to protect long-run reputation.